Published November 4, 2026 by Redbud Ridge Roofing
Every insurer and policy is different, so your own policy and agent are the final word. Still, most roof claims follow a similar path, and knowing it helps you avoid surprises. This guide explains each stage, the numbers you will see, and the records that are worth keeping. We are roofers rather than lawyers or adjusters, so treat this as a practical overview and check anything important with your carrier. If you would like help with the paperwork, see roof insurance claim help.
Before you file: read your declarations page
A few minutes with your policy can save a lot of frustration. Look for these items on the declarations page and in the policy itself:
- Wind and hail deductible. In Oklahoma this is often a percentage of your dwelling coverage rather than a flat amount. One percent of $300,000 is $3,000, and two percent is $6,000.
- Roof settlement type. Replacement cost, actual cash value, or a roof payment schedule based on age.
- Cosmetic damage exclusions. These commonly apply to dents on metal roofs that don't affect function.
- Ordinance or law coverage. This can help pay for code-required items the old roof didn't have.
- Reporting deadlines. Policies usually set time limits for reporting a loss and for finishing repairs.
Next, compare your deductible with the likely cost of repair. If the damage is minor, a claim may gain you nothing while still appearing on your claim history. A roof inspection with photos gives you the information to decide. Ask your agent how a claim could affect your premium or renewal if that is a concern.
1. Document and report
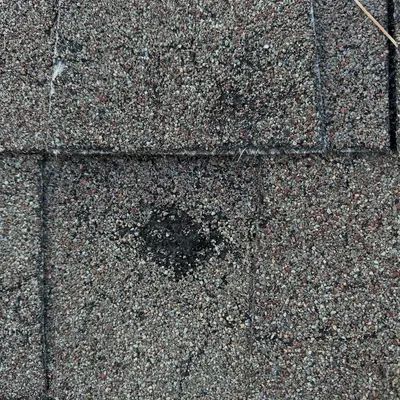
Photograph damage from safe locations, note the storm date, and report the claim according to your policy's instructions. Don't delay, because policies usually set time limits, and older damage is harder to tie to a specific storm. Most carriers accept claims by phone, app or website. Write down your claim number, the name of your adjuster, and the date of every conversation.
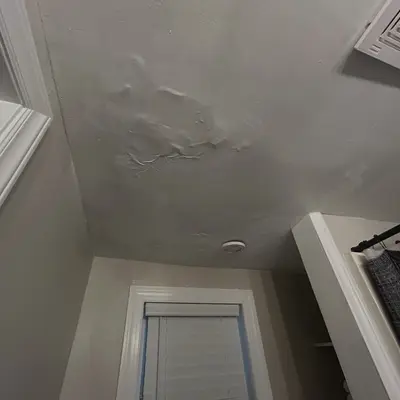
If water is getting in, protect the home right away with a tarp or temporary repair, and keep the receipts. Most policies require reasonable steps to prevent further damage. Photograph conditions before anything is moved. Don't throw away damaged materials until you have documented them, and your adjuster may want to see them.
2. The adjuster's inspection
Your insurer sends an adjuster to inspect the roof, sometimes a staff adjuster and sometimes an independent adjuster hired for storm work. After a major storm, this can take longer than usual. You can ask your roofer to attend and point out what they found. Good adjusters welcome the documentation, since test squares, photos and measurements help them do their job.
During the visit the adjuster will check each slope, count hits in test squares, look at soft metals and note the age and condition of the roof. They then write a scope that lists the covered items and their prices. Many carriers use estimating software with a local price list, so don't be surprised if line items look unfamiliar. The adjuster doesn't always have the final say, because coverage decisions may be reviewed by the carrier.
3. Understanding the numbers
Your estimate or statement of loss usually shows several figures. Here is what they mean:
- Replacement cost value (RCV): the estimated cost to replace the damaged items with similar new materials.
- Depreciation: the reduction for age and wear.
- Actual cash value (ACV): RCV minus depreciation.
- Deductible: the amount you are responsible for.
- Net claim or first payment: usually ACV minus the deductible.
Here is a simple example with round numbers. Say the RCV is $16,000, depreciation is $4,000 and your deductible is $3,000. On a replacement cost policy, the first check is $9,000 ($16,000 minus $4,000 minus $3,000). After the work is complete and you submit the required paperwork, the carrier may release the $4,000 holdback. Your share remains the $3,000 deductible, plus any upgrades you choose. On an actual cash value policy, that $4,000 generally isn't paid back, so your share would be $7,000. These numbers are only an illustration, and yours will differ.
A mortgage company may also be named on the check. In that case, the lender may hold the funds and release them in stages. Call your lender early to learn their process, because it can affect when your contractor can start.
4. Reviewing the scope
Compare the scope to what your roof needs. Drip edge, starter, flashing, vents, ridge caps, ice and water membrane, and decking are commonly discussed items. Check that the measurements match the actual roof and that each slope is accounted for. Gutters, screens and fences may also be part of the same loss if the storm damaged them.
If something appears to be missing, your contractor can provide documentation, and you can ask your insurer to take another look. This is often called a supplement. A good supplement shows why the item is needed, with photos, measurements or code references. It is a normal part of the process, but your insurer makes the decision. Contractors can document and explain the work, but they should not be negotiating your coverage or promising that a carrier will pay.
5. Paying your deductible
Plan to pay your deductible. Be cautious of any offer to waive it or hide it inside an inflated invoice, since that can create serious problems with your claim. An honest invoice should show the work actually performed at the actual price. Ask your agent if you're unsure. If paying a large deductible at once is difficult, ask about payment plans or financing early in the process, rather than looking for a contractor who promises to make it disappear.
6. Choosing materials and upgrades
Your claim pays for like-kind replacement, but you can often choose to upgrade at your own cost. Popular choices include impact-rated shingles, better ventilation and upgraded underlayment. Our guide to Class 4 shingles explains how to figure out whether premium credits make that upgrade worthwhile. Be sure the contract clearly separates insured work from upgrades, so that everyone can see what is being paid for.
7. Closing it out
When the work is finished, you may need to submit a final invoice, photos or a certificate of completion before the depreciation is released. Check the deadline, as some policies limit how long you have to complete repairs and collect the holdback. Keep the signed contract, invoices, photos and any manufacturer paperwork. These records help with depreciation release, future claims and selling your home. It is also smart to note your new roof's install date, as insurers often ask.
If your claim is denied or comes in low
A denial is not always the end of the conversation. Read the letter and identify the exact reason. Common reasons include wear and tear, cosmetic damage exclusions, a missed reporting deadline, or damage that the carrier does not connect to the reported storm. If you think a fact was missed, you can usually request a re-inspection and provide additional photos, weather data or an independent report.
If you still disagree, ask your carrier about its appeal process and whether your policy has an appraisal clause. The Oklahoma Insurance Department accepts consumer complaints and offers information on claims. Licensed public adjusters work for policyholders for a fee, and an attorney can advise you on legal rights. A contractor can give you documentation, but these are separate roles.
How long a claim usually takes
Timelines vary with the carrier, the size of the storm and how complete your documentation is. A simple claim may move from filing to payment in a few weeks. After a major hailstorm, adjusters and contractors can be stretched thin across the region, so the same claim could take much longer. Supplements, mortgage company requirements and material shortages can add more time. Respond promptly when your carrier asks for something, and keep a note of who you spoke to and when.
Watch two dates in particular. The first is the deadline for reporting the loss. The second is any deadline for completing repairs and collecting recoverable depreciation. If the work may run late, ask your carrier about an extension in writing before the deadline passes.
Who does what in a claim
Claims can feel confusing because several people are involved, and each has a different role. Knowing who does what helps you take your question to the right person.
- Your agent explains your policy and how a claim could affect your coverage.
- The adjuster inspects the loss and writes the estimate for the carrier.
- The carrier decides what is covered and issues payment.
- Your roofer documents the damage, explains the work and completes the repair under contract.
- A public adjuster, if you hire one, represents you on the claim for a fee and must be licensed.
- An attorney can advise you on your rights if a serious dispute arises.
Be wary if anyone blurs these roles. A contractor who claims to handle your whole claim, or who asks you to sign away your rights to deal with the carrier, may be going beyond what they should do. You remain the policyholder, and it's reasonable to stay involved in every conversation and to ask for copies of everything that is sent on your behalf.
Common mistakes to avoid
- Waiting months to report damage you already knew about.
- Signing a contract or assignment of benefits before you understand it.
- Throwing away damaged materials before they are documented.
- Assuming that a free inspection means a claim will be approved.
- Spending the insurance check on other things before repairs are complete, as the holdback and your mortgage terms may depend on the work.
- Choosing a contractor based only on who promises the largest payout.
If you would like photos and an honest read on your roof before you call your carrier, see our roof insurance claim help page or request a visit.